Business Income Verification Can Save Havasu CRE Deals from Stalling at Financing
Commercial deals in Lake Havasu City rarely collapse at the closing table. They typically fall apart in the financial package. Business-tied real estate income verification is where deals get made or quietly die, and most buyers never see it coming.
A standard investment property runs relatively clean: the lease is the lease, taxes are verifiable, and insurance is a known line item. When the property is tied to a business, the numbers get slippery fast. That is where real underwriting earns its value.
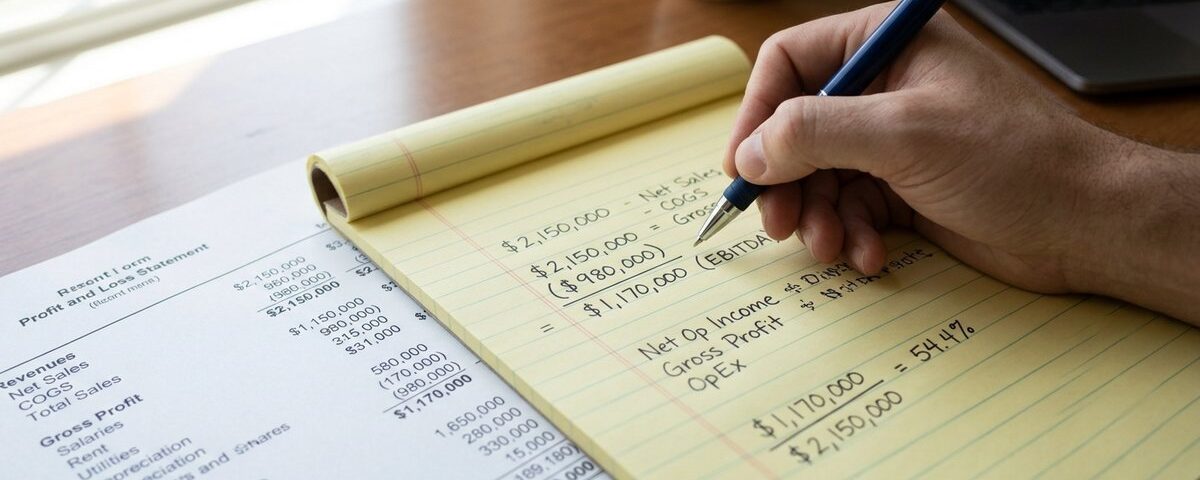
When a business occupies commercial real estate, the seller's stated income is a starting point. Years of tax-minimization strategies leave profit and loss statements that obscure true performance. The real number requires stripping out personal expenses, adjusting for non-operational charges, and running cap rate math against what the market will actually support.
Business Income Claims Rarely Match the Financials
These deals typically run into issues in the gap between what the seller claims a property earns and what the documents show. That gap almost always traces back to the owner's tax strategy. The owner has spent years working to minimize taxable income, and their P&Ls reflect that effort.
Expenses that would typically be personal find their way to the business books. You might see a motor home payment, kids' activities, or family insurance. As a result, the net income looks thin or nonexistent even when the operation is healthy.
Lenders and buyers make decisions off that same document. When a seller claims strong earnings but the P&L shows near-zero income, financing becomes nearly impossible.
Buyers cannot get approved on income that is not on paper, and sellers cannot defend a price the numbers will not support. That is why so many business-involved deals stall before they reach an offer.
Finding the Real Income on a Business Property
The tool that cuts through the noise is an EBITDA analysis: earnings before interest, taxes, depreciation, and amortization. Removing non-operational items, personal charges, and accounting-driven deductions reveals what the business actually produces. That is the number a realistic buyer can underwrite and a lender can approve.
The adjustments most commonly hide in three places:
- Personal expenses loaded onto the business books
- Depreciation, which makes income disappear on paper while cash continues to flow
- Owner perks unrelated to operations that push stated earnings toward zero
Randy Shuffler has run this process on enough transactions across Lake Havasu City and the Kingman corridor to spot the patterns quickly. When the P&L looks thin, and the seller insists the business is profitable, the answer is usually in the addbacks.
"A lot of people do not want to pay taxes, and a lot of times you can take that stuff out of there. There are a couple different formulas. EBITDA is one, and you're taking out interest, depreciation, and amortization. But a lot of people will put their motor home insurance, or their kids' stuff, on there. So they'll put all their personal things on there, and their profit and loss ends up looking like it's zero. So you can take all that stuff out and back it in, hey, this is actually what the real number is." – Randy Shuffler, Founder and Commercial Real Estate Agent, Lake Havasu City Commercial
Turning Real Income Into Supportable Value With Cap Rate Math
Once you establish true net income, the path to value is direct. Subtract verified expenses from gross income to reach net operating income, then divide by the applicable cap rate. The result is what a buyer should pay, built on real numbers rather than seller assumptions.
Take a small investment property leasing for $2,000 a month:
- Gross income: $24,000 a year
- Expenses: $3,000 taxes, $2,000 insurance, $3,000 maintenance
- Net operating income: $16,000
- Supportable value at a 6.5 cap rate: roughly $246,000
"If it's an investment property, they're paying two thousand a month for this little place, times twelve, that's twenty-four thousand. Then your taxes are three thousand, insurance is two thousand, maintenance is three. You end up at sixteen grand. Divide that by a six-and-a-half cap rate, and it gives you a value of two hundred forty-six thousand. All of that's pretty simple and easy to figure out. Insurance has been a real pain lately. That's the one thing I used to have a good standard on, but now it's so expensive." – Randy Shuffler, Founder and Commercial Real Estate Agent, Lake Havasu City Commercial
Insurance costs across Mohave County have shifted enough that historical figures on seller spreadsheets are often unreliable. Get a current quote rather than modeling off what the seller paid three years ago.
The Arizona Department of Real Estate requires licensed brokers to present material facts accurately in commercial transactions, including income representation. That obligation exists on both sides of the table. A seller who misrepresents income creates liability, and a buyer who accepts stated income without verification assumes the seller's risk.
Rising Interest Rates Raise the Bar for Cap
With interest rates where they are, a buyer can place capital in U.S. Treasury securities and earn around six percent. They get that six percent with no credit risk and no operational exposure. That benchmark shapes every commercial underwriting conversation.
A deal priced at a four or five cap does not clear that bar, which is why overpriced listings sit. Higher interest rates push buyers to demand higher cap rates, and higher cap rates mean lower valuations regardless of construction cost or inflation. Sellers who price off construction cost or gut feel will watch their listings age.
The benchmark rate environment comes from the Federal Reserve's monetary policy framework. When the risk-free rate is elevated, income-producing real estate must offer a meaningful premium to attract private capital. Properties in the 6.5 to 7.5 percent cap rate range draw serious underwriting interest. Lower yields require exceptional tenant quality, long-term lease security, or a flexible seller.
What to Do Before Making an Offer on a Business Property
None of this means you should stay away from these properties. You just need to do the math before committing.
Before writing an offer, buyers should:
- Treat the seller's stated income as a starting point, then review the actual financial documents.
- Adjust for personal and non-operational charges.
- Verify expenses against current market costs, including insurance.
- Run cap rate math against today's investment alternatives, not 2021 rate assumptions.
A buyer who underwrites on true net income has a defensible position with the lender, the appraiser, and their own risk tolerance. A buyer who pays on claimed income and later discovers the real figures runs into trouble.
True-net underwriting works the same whether you are evaluating a retail strip in the South Gate District or a warehouse in the Kingman corridor. The only difference is that the inputs change.
My post about what California investors get wrong about Havasu cap rates touches on many of these related issues. It's a good read to learn how cap rate logic works across different Havasu asset classes.
FAQs About Business Income Verification in Commercial Real Estate
Why do commercial deals involving businesses fail more often than standard investment properties?
Standard investment properties with third-party leases document income on paper, so a lender can approve them from the lease. Business-involved deals depend on the owner's reported performance, which years of tax-minimization decisions often distort. When stated and real income diverge, financing is set up to fail before an offer is made.
What specific documents should a buyer request to verify business income?
Verifying business income requires the following:
- Three years of federal tax returns
- Full profit and loss statements for the same period
- Bank statements confirming actual cash flow
When these conflict with the seller's verbal income claims, that gap is where your due diligence starts.
How does EBITDA analysis apply to commercial real estate income verification?
EBITDA removes interest, tax-strategy effects, depreciation, and amortization to show what the business produces from operations. In business-involved sales, it also strips out personal expenses, leaving a defensible figure a lender can approve.
What is net operating income and how is it different from what a seller reports?
Net operating income is gross income minus verified operating expenses. It excludes mortgage payments, depreciation, and personal charges. Seller P&Ls often include items that do not belong in NOI, so rebuild it from source documents rather than the seller's summary.
Can a seller legally include personal expenses on a business P&L?
Tax strategy is between an owner and their accountant, and questions about tax liability belong with a qualified tax attorney. For buyers, the practical issue is simpler: personal expenses understate net income and make financing harder to secure. Addback analysis restores the real income picture.
How much has insurance changed the underwriting math for Havasu commercial properties?
Significantly. Costs across Mohave County have risen enough that a seller's historical figure can introduce real error. Get a current quote for the specific property and use it in your expense calculations.
When does a commercial property income verification problem become a financing problem?
Immediately. Lenders underwrite against documented income. When the seller's claimed earnings are higher than what the documents show, you have a financing problem. The buyer cannot bridge that gap with a verbal assurance. The deal stalls unless the seller provides documentation that actually supports the income claim. Either that, or the buyer must adjust the offer price to reflect what the documents show.
Get the Real Number Before You Make an Offer
The gap between what sellers claim and what the financials support is the most common reason commercial deals in Lake Havasu City stall or collapse. Keeping the deal on track requires true-net income verification, EBITDA-style addback analysis, and cap rate math built on verified expenses. That's what separates a defensible offer from one that falls apart at the lender's desk.
Shuffler Commercial Realty helps buyers work through this analysis on commercial properties across Lake Havasu City, Kingman, and Mohave County. If you are evaluating a business-involved commercial opportunity and want to see what the numbers actually say, send me the address for a true-net snapshot.